Leaving an IRA to a Special Needs Trust in Illinois Without Losing Benefits
If the beneficiary form names a person who receives means-tested benefits directly, the inherited account lands in that person's own name, where it can count against SSI or Medicaid. Naming a properly written special needs trust instead keeps the account with a trustee. The trust should already be signed before the owner dies, be named on the form, and meet the federal rules for a trust that is allowed to be an IRA beneficiary (26 CFR 1.401(a)(9)-4). Its wording decides how fast the money must come out and who pays the tax, so it should be checked against the will, any living trust and the plan's own paperwork before anyone signs.
Short answer: yes, you can name a trust as the beneficiary of a retirement account, and for a family member who receives benefits it deserves a close look. The details matter, because the form that says naming a special needs trust as an IRA beneficiary is only one document in a set. This guide is for a parent or grandparent holding a beneficiary form, or an adult child helping them, who wants to know what to put on the form and what the trust has to say.
It reads the federal tax rules for retirement accounts, the Social Security program rules for trusts and retirement funds, and the Illinois Trust Code, and it says where those texts stop.
Why Not Just Name the Child on the Form?
Because the account would then belong to the child. Social Security's rules say that if an individual can withdraw any part of a retirement fund, it is a resource in the amount currently available (SSA POMS SI 01120.210). The page we reviewed speaks to retirement funds in general and does not address an account inherited from someone else, so the safe assumption is that an account in the person's own name needs a close look before it is allowed to sit there. SSI has a resource limit, and a large inherited balance can pass it quickly.
Money management is the second reason. A person who needs a trustee for everyday decisions may not be able to manage a retirement account, take required withdrawals on time or deal with the tax return that follows. A trust puts a named person in charge of all of that.
If you are still deciding which tool fits which dollars, start with our decision guide on ABLE accounts and special needs trusts, then come back here for the retirement account.
Four Ways the Beneficiary Form Can Be Filled In
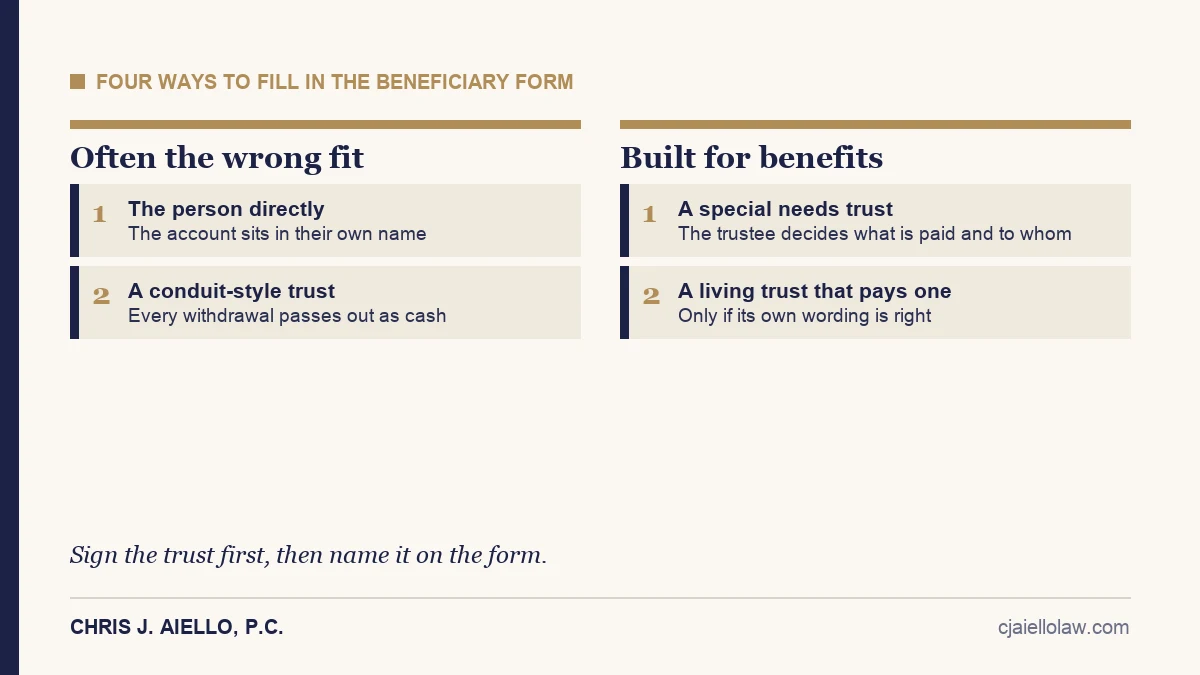
Most families end up with one of four versions. The table describes what each tends to do. Every cell depends on the trust's wording and the benefit program, so treat it as a way to ask better questions.
| Who is named on the form | What it usually means for means-tested benefits | Who is taxed on withdrawals (general rule, confirm with a CPA) | Where it can go wrong |
|---|---|---|---|
| The person with the disability, directly | The account is in the person's own name. If the person can withdraw from it, the program rules treat what is available as a resource (SI 01120.210) | The person, on what they withdraw | Nobody is named to manage it, and the balance may count against eligibility |
| A trust that must pass every withdrawal straight to the person (often called a conduit trust) | Cash paid to the beneficiary is unearned income under the trust rules (SI 01120.200 E.1.a), so passing every withdrawal out can mean passing cash out | Generally the person, on what the trust passes to them | The trust is a pipe, so it protects the account but not the benefit |
| A third-party special needs trust that lets the trustee keep money inside (often called an accumulation trust) | If the person cannot revoke the trust or direct its use for support, the principal is generally not a resource (SI 01120.200 D.2). Payments to third parties are generally not income unless they provide shelter or certain other items the rules count (E.1.b and E.1.c) | Whoever receives the income: the trust on what it keeps, the person on what is paid to them | The trust is not signed before death, or its wording does not meet the federal rules for a trust that can be named |
| A living trust, which then pays a special needs trust | Depends entirely on what the living trust says. It adds a layer between the account and the person | Depends on the trust terms | The living trust gives the account to every beneficiary alike, or pays the person outright |
What Does the Trust Have to Say to Work as the Beneficiary?
Two layers of rules apply, one federal and one from Illinois.
The federal tax regulation lists four requirements for a trust whose beneficiaries are to be treated as the account owner's designated beneficiaries (26 CFR 1.401(a)(9)-4(f)(2)). The trust must be valid under state law. It must be irrevocable, or become irrevocable by its terms when the owner dies. Its beneficiaries must be identifiable from the trust instrument. And the documentation requirements must be met, which generally means giving the plan administrator either a list of the beneficiaries or a copy of the trust by October 31 of the year after the owner's death.
On the Illinois side, the trust must satisfy the Trust Code. A trust is created only if the person creating it has capacity and intends to create it, the trust has a definite beneficiary (the statute lists narrow exceptions, such as charitable and animal trusts, that do not apply to a trust for a person), the trustee has duties, and the same person is not the sole trustee and the sole beneficiary (760 ILCS 3/402). A trust can be created by a will or by a transfer during the owner's lifetime (760 ILCS 3/401). The Code allows a trust to come into being at death, but a trust that is signed while the owner is alive leaves more room to check the wording before it matters.
Calling the document a special needs trust does not satisfy any of this by itself. The test is what the instrument says.
How Fast Does the Money Come Out, and Who Pays the Tax?
Federal law generally requires most beneficiaries of an inherited defined-contribution account to take everything out within 10 years, and in some cases to take yearly withdrawals along the way (26 U.S.C. 401(a)(9)(H), which applies to IRAs through section 408(a)(6)). A longer payout is allowed only for an eligible designated beneficiary, a category that includes an individual who is disabled within the meaning of section 72(m)(7) of the tax code. That is a federal tax definition, and it is not automatically the same as a finding by a benefits agency, so do not assume one answers the other.
The statute also has a special rule for trusts built for disabled or chronically ill beneficiaries, which it calls an applicable multi-beneficiary trust. In that kind of trust, no other beneficiary may have a right to the account until the death of all of the disabled or chronically ill beneficiaries (26 U.S.C. 401(a)(9)(H)(iv)). The regulation says the disabled beneficiaries of such a trust are treated as eligible designated beneficiaries even when the trust's other beneficiaries are not. Whether a particular trust fits depends on its wording, which is one more reason to have it read before the form is signed.
Tax follows the same logic as the benefits table. A trust that keeps income inside is a separate taxpayer. A trust that pays income to the person passes that income to the person's return, and for SSI purposes cash paid to the person is income. The sections we reviewed do not set out tax rates or a way to predict the bill, so ask the attorney and the CPA to run the numbers for your account before you choose between the versions in the table.
Check These Before You Sign the Form
- Is the trust already signed? A plan to write one later leaves the form pointing at a document nobody has read.
- Is the trust named exactly as it appears on the document, with its date?
- Who is the contingent beneficiary if the trust cannot take the account?
- If a spouse is the first beneficiary, what happens when the spouse also dies or disclaims? Ask what the account does next and who it reaches.
- Does the will or any living trust try to leave the same account to someone else? A beneficiary designation generally controls the account, so a will that disagrees with the form does not fix it. The will versus trust guide explains how the pieces fit together.
- Has the plan's own beneficiary paperwork been checked? Some plans have their own forms and limits.
- Does the trustee know the role, and is there a named successor?
When to Bring in an Estate Planning Attorney
Bring one in before the form is signed, not after. The same document can protect a benefit or put it at risk, and the difference is in the wording. Planning for a family member with a disability usually includes the trust, the beneficiary forms and a will that points the same way, and trusts in Illinois covers how a trust is set up and funded. If your child is about to turn 18, our guide to the decisions that come at 18 covers the paperwork around that birthday.
Holding a beneficiary form for a family member with a disability?
Chris J. Aiello, P.C. has helped DuPage County families plan since 1990. Bring the account statement, any trust and the form, and we will walk through which version fits.
Schedule a ConsultationSources: 26 U.S.C. 401(a)(9) · 26 CFR 1.401(a)(9)-4 · SSA POMS SI 01120.200 · SSA POMS SI 01120.210 · 760 ILCS 3/401 · 760 ILCS 3/402
General information about federal and Illinois law, current as of November 2026. This guide describes the sections cited; your family's facts may call for a different answer. It is not legal advice and it does not create an attorney-client relationship.